FHA vs Conventional Loan: Which Is Better for Your New Home?
In this article
"FHA loans let you buy with as little as 3.5% down if your credit score is 580 or higher, but with a typical small down payment you pay FHA mortgage insurance for the life of the loan. Conventional loans can start at 3% down, and the private mortgage insurance (PMI) on them must come off automatically once you reach 78% of the home's original value. Which is better depends on your credit, your down payment and how long you plan to keep the loan.
Below, we compare FHA and conventional loans side by side with sourced rules, show an example payment, and cover what changes when you buy a brand-new home.
What is the difference between an FHA loan and a conventional loan?
An FHA loan is insured by the Federal Housing Administration, part of the U.S. Department of Housing and Urban Development (HUD). A conventional loan is not backed by a government agency. Many conventional loans follow rules set by Fannie Mae or Freddie Mac.
The biggest differences come down to four things:
How much you must put down
The credit score you need
How mortgage insurance works, and whether it ever goes away
How much you can borrow
How much do you need to put down on FHA vs conventional?
FHA: HUD's handbook says the borrower ""must make a Minimum Required Investment (MRI) of at least 3.5 percent."" The maximum loan-to-value on a purchase is ""96.5 percent"" (HUD Handbook 4000.1).
Conventional: Fannie Mae offers ""97% loan-to-value"" financing, which means 3% down (Fannie Mae). For its standard 97% loan, ""at least one borrower must be a first-time homebuyer."" Fannie Mae's HomeReady loan, made for ""borrowers with lower or nontraditional incomes,"" also offers ""down payments as low as 3%,"" and ""you don't have to be a first-time homebuyer to be eligible"" (Fannie Mae HomeReady).
So on paper, a conventional loan can need a smaller down payment than FHA.
What credit score do you need for FHA vs conventional?
FHA: A score ""at or above 580"" is ""eligible for maximum financing."" A score ""between 500 and 579"" is ""limited to a maximum LTV of 90%,"" which means at least 10% down. Below 500, a borrower ""is not eligible for FHA-insured financing"" (HUD Handbook 4000.1).
Conventional: This changed recently. Fannie Mae's Selling Guide now says ""a minimum credit score is not required for DU loan casefiles."" DU is Fannie Mae's automated approval system. For loans approved by hand, the minimum is 620 for fixed-rate loans (Fannie Mae Selling Guide B3-5.1-01). The change took effect for new casefiles created on or after Nov. 16, 2025.
That does not mean any score gets approved. Lenders can still set their own minimums, and your score still affects your rate. Read more in what credit score you need to buy a house.

How does mortgage insurance work on FHA vs conventional?
This is where the two loans differ the most.
FHA mortgage insurance (MIP) has two parts:
An upfront premium of 1.75% of the base loan amount (HUD Mortgagee Letter 2023-05).
An annual premium, paid monthly. For a loan longer than 15 years and up to $726,200, HUD's chart sets it at 0.55% a year when you put down less than 5%, and 0.50% a year when you put down 5% or more (HUD Handbook 4000.1, Appendix 1.0).
How long does annual MIP last? Under HUD's chart, it lasts 11 years only if your loan-to-value is 90% or less, which means at least 10% down. With less than 10% down, it lasts for the mortgage term.
Conventional PMI works differently. The CFPB says you can ask to cancel PMI when your balance ""is scheduled to fall to 80 percent of the original value of your home."" And your servicer ""must automatically terminate PMI on the date when your principal balance is scheduled to reach 78 percent of the original value of your home,"" as long as you are current on payments (CFPB).
There is no single government price chart for PMI, so ask your lender for a quote. Learn more in our guide to PMI.
FHA vs conventional: what does the monthly payment look like?
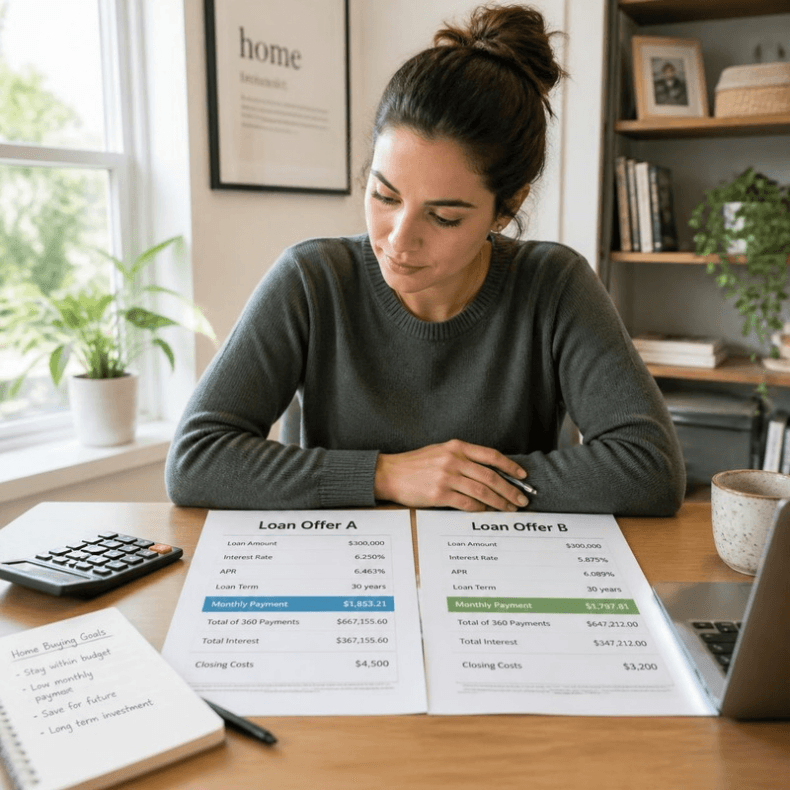
Here is an EXAMPLE only on a $400,000 home. To show just the effect of the loan rules, we use the same rate for both: 7.28%, the 30-year fixed average in Freddie Mac's survey for the week of Oct. 1, 2026 (Freddie Mac PMMS). Your real rates will differ by loan type, credit and lender.
EXAMPLE: $400,000 home | FHA, 3.5% down | Conventional, 3% down |
|---|---|---|
Down payment | $14,000 | $12,000 |
Base loan | $386,000 | $388,000 |
Upfront mortgage insurance | $6,755 (1.75%), added to the loan in this example | None |
Loan amount used below | $392,755 | $388,000 |
Principal and interest at 7.28%, 30 years | about $2,687 | about $2,655 |
Monthly mortgage insurance | about $177 in year one (0.55% of $386,000 ÷ 12) | Quote from insurer |
When mortgage insurance ends | Mortgage term (less than 10% down) | Must end automatically at 78% of original value |
HUD says the upfront premium ""must be entirely financed into the Mortgage or paid entirely in cash"" (HUD Handbook 4000.1). Taxes, homeowners insurance and any community fees are extra. Your lender will give you the exact figures on a Loan Estimate.

How much can you borrow with FHA vs conventional?
For 2026, the baseline conforming loan limit for a one-unit home is $832,750, and the ceiling in high-cost areas is $1,249,125 (FHFA).
FHA limits are set by county. For 2026, HUD's one-unit floor is $541,287 and the one-unit ceiling is $1,249,125 (HUD Mortgagee Letter 2025-23). Ask your lender for the limit in the county where you are buying.
Can a builder or seller help with closing costs on FHA or conventional?
Yes, within limits. These are called interested party contributions.
FHA: contributions ""exceeding 6 percent are considered an inducement to purchase,"" and they ""may not be used for the Borrower's MRI,"" meaning your 3.5% down payment (HUD Handbook 4000.1).
Conventional (Fannie Mae), for a home you live in: 3% if your loan is more than 90% of the value, 6% from 75.01% to 90%, and 9% at 75% or less (Fannie Mae Selling Guide B3-4.1-02).
So with a small down payment, FHA can allow a larger builder contribution than a conventional loan. That can matter when a builder offers help with closing costs or a rate buydown.
What this means for new-construction buyers
Both loan types can be used on a new home, but each has rules for new construction.
For FHA, HUD's handbook says ""New Construction refers to Proposed Construction, Properties Under Construction, and Properties Existing Less than One Year."" The lender must collect builder forms, including ""form HUD-92541, Builder's Certification of Plans, Specifications, and Site"" and ""form HUD-92544, Warranty of Completion of Construction"" (HUD Handbook 4000.1). The handbook also requires form HUD-NPMA-99-A, a termite protection guarantee, for new construction unless the county is on HUD's exception list. Ask the builder early whether it provides these forms.
A few more tips for new-build shoppers:
Compare the builder's contribution under each loan. The limits above can change which loan gets you more help.
Watch the clock. If your home takes months to finish, your rate and paperwork may need updating. See when to lock your mortgage rate.
Ask about removing mortgage insurance later. With conventional PMI, you can plan for the 80% and 78% marks.
Buying in Florida? See using an FHA loan on new construction in Florida. For today's numbers in a specific community, call 561-704-0091.

Common Questions
Is FHA or conventional better for a first-time buyer?
It depends on your credit and down payment. FHA allows 3.5% down with a 580 score. Conventional can start at 3% down, and its PMI must end automatically at 78% of the original value.
Does FHA mortgage insurance ever go away?
Under HUD's chart, annual MIP lasts 11 years if your loan-to-value is 90% or less, meaning at least 10% down. With less than 10% down, it lasts for the mortgage term.
What is the minimum credit score for a conventional loan?
Fannie Mae's Selling Guide says a minimum score is not required for loans run through its automated system, DU. Manually underwritten fixed-rate loans need 620. Lenders can still set their own minimums.
How much is the FHA upfront mortgage insurance premium?
It is 1.75% of the base loan amount. On a \$386,000 base loan, that is \$6,755.
Can I use an FHA loan on a brand-new home?
Yes. HUD treats proposed homes, homes under construction and never-occupied homes less than one year old as new construction. The lender must collect builder forms, including a warranty of completion of construction.
How much can a builder pay toward my closing costs?
On FHA, contributions above 6% are treated as an inducement to purchase. On Fannie Mae conventional loans for a home you live in, the limit is 3%, 6% or 9%, depending on your loan-to-value.
Ready to take the next step?
Call 561-704-0091 to talk with a National House Search specialist, or Schedule a visit.
Related reading: What is PMI (private mortgage insurance)? · Can you use an FHA loan on new construction in Florida? · What credit score do you need to buy a house?
This is general information, not financial, tax or legal advice. Figures checked October 8, 2026."